
30.01.25 - No clear direction
Neither corporate earnings nor the latest Fed decision have provided a clear direction for the market.
Yesterday, the Fed left interest rates unchanged as widely expected. With the press release, Fed Chairman Jerome Powell sent the message that the US central bank intends to keep the interest rates unchanged for the foreseeable future.
Meanwhile, reactions to earnings releases from big tech companies are mixed. While Meta and Tesla are trading higher, Microsoft takes a dip in pre-market trading session.
Markets: China’s market closed for the week (Chinese New Year). The German index DAX is on new record high,
Interest rates decline,
My View: Fed Chairman Jerome Powell’s recent comments did not significantly impact the equity markets. However, interest rates started to decline as investors had concerns on higher inflation and higher interest rates. The market is now pricing in two rate cuts in 2025 in the US, a notable shift from expectations some days earlier in January, when there were discussions about a potential rate hike among investors.
The decline in interest rates is a positive development for my tactical position in long-term Treasuries, as lower rates enhance their value.
28.01.25 - What’s next?
A turbulent start into the week, marked by Nvidia's largest single-day market cap drop of nearly USD 600 billion following the DeepSeek story. This sets the stage for a pivotal week ahead, with the Fed's decision on Wednesday and a wave of key earnings reports, including those from major tech companies.
Markets: Tech sector tries to stabilize with Nasdaq Futures marginally in plus.
My View: Buy the dip? Lately it has always been a successful strategy. You can always find arguments why this time is different. However, it is not about what a single analyst or even I believe, it is about gauging the sentiment and conclusions of the broader market. Following the rebound move this morning, which looks so far rather shy, the market participants did not make their decision yet. This can change any hour though. Looking at cryptos, some speculation is already back, as I see a partial offset of yesterday’s losses.
I am following the current situation closely. Such a scenario I do not challenge, yet. Instead, I prefer to wait for clarity or an indicator showing me a clear buy signal before making a significant move back into the tech sector, especially since I am investing my own money and running a portfolio with good risk appetite already.
This week has definitely the potential for further volatility as Fed decision and earnings releases are on the agenda. And we keep president Trump in mind who also tries to take bigger influence on the interest rate decision.
27.01.25 - Big unwinding of momentum strategies
Amid today’s market turmoil, momentum strategists appear to be unwinding their positions which triggers a substantial reversal in performance trends. Recent laggards (like Nestlé) are emerging as today’s winners, while former high-flyers like Nvidia and similar stocks are now among the biggest losers.
Momentum investing is a strategy of buying stocks or other securities that have had high returns over the past days and weeks, and selling those that have had poor returns over the same period.
Markets: Tech sector with semiconductors heavily down as well as the utilities sector. Cryptos tried to rebound without success yet.
My View: So far it is not a market correction as there is no broad sell-off. The focus remains on the unwinding of momentum trades, and it will be interesting to see how long this trend persists.
This unexpected sharp correction on the tech side plays into my cards. I have taken advantage of the significant drop by closing my short positions in Constellation Energy, Vistra, Nvidia and half of my semiconductor short position (ETF).
While I am not personally invested in cryptocurrencies, I closely monitor their movements as a gauge for overall market sentiment.
27.01.25 - Big shake up
A Chinese startup, Deepseek, is shaking up the AI industry and is challenging the US dominance. Deepseek has launched a new AI model which industry experts claim to be as good or even better than those developed from tech giants like Google or OpenAI. While Silicon Valley firms have invested billions in developing their models, Deepseek achieved this milestone with a remarkably modest investment of just USD 5.6 million.
Markets: Nasdaq Futures down more than 3% (time of writing), cryptos sell-off, China’s stock markets stable with solid gains. Defensive stocks in the green, interest rates down, Swiss Franc stronger with safe haven demand arising, volatility jumps
My View: Is there an AI disrupter around the horizon? The recent news has definitely the potential to challenge the entire valuation of the AI industry and could burst the AI bubble.
For nearly a year now, I have maintained the view that the AI sector appears to be an overly crowded space. While speculators are now retreating from the markets in fear, I remain calm, with my well-diversified and stable portfolio. My short positions on some crowded stocks in that sector and the long volatility trade are kicking in. My latest addition to this list of short positions, as of last Friday, include Vistra and Constellation Energy, among the top losers in pre-market today.
23.01.25 - More clarity in Trump’s strategy
Another politically driven day. Today, president Trump joined the World Economic Forum (WEF) in Davos via video. During his speech, he outlined several key points regarding his political strategy:
- lower interest rates
- lower oil price
- lower tax for corporates as an incentives to produce in the US - else countries would face tariffs
- Stopping the war through increased sanctions on Russia - lower oil prices should force Russia to join discussions
- Europe: A warning of tariffs if the EU continues to treat the US and its institutions 'unfairly' in terms of trade and regulations
- US, to be the capital for cryptos
Markets: Oil prices reacted promptly with a correction. Cryptos down for the day in a volatile trading. Stocks indices gaining across the globe, tech stocks lagging for once. Interest rates with some increase, US dollar trading sideways in a broad range.
My View: At the moment, it is crucial to closely monitor the news and the impacts on all financial market indicators. President Trump's speech was particularly interesting to follow, as it provided to me greater clarity on his strategy and political game plan.
The possibility of tariffs fuels fears of inflation among investors. However, lower oil prices could offset some of the upward pressure on prices. Meanwhile, lower interest rates would decrease borrowing costs, potentially boosting investment and consumption.
It will be interesting to see if market participants interpret this similarly - that inflation concerns may be overstated if tariffs are implemented. If not, this could have major impact on markets.
Following the speech, I took immediate action to avoid downside, closed today my long position in WTI crude oil at a price of USD 75 a barrel, entered at USD 67, implemented via a leveraged ETF, see my blog article: “Once called the «Black Gold» - did oil lose its shine?, 1 October 2024.
I gained a clearer understanding of the political game plan after analyzing the speeches and recent news flow. As a result, my concerns and uncertainties have diminished, leading me to identify an opportunity to increase the risk exposure in my portfolio.
I reinvested the proceeds directly into US Small Caps (ETF) and the defensive Food & Beverages sector (ETF) which has declined overproportionally since mid December due to tariff concerns, rising interest rates and strengthening US dollar.
In case risk on sentiment persists, I plan to further increase my equity exposure.
22.01.25 - Fresh optimism in the tech sector
What a spark in the tech sector. The mix of news from White House and Netflix with the release of its fourth quarter results gave the tech sector a big boost, starting during yesterday’s late trading session already.
President Trump announced a joint venture, Stargate, to invest billions in the artificial intelligence (AI) infrastructure over the next years. Furthermore he is considering a 10% tariff on all Chinese imports, could be in place by beginning of February. Mexico and Canada are braced for tariffs of 25%. Fresh tariff threads against the European Union also on the agenda.
Markets: Today’s market saw sharp contrasts. China’s stock markets down while European markets follow the US strength.
Crypto investors continue to wait on the sideline, hoping for a push from politics. In the US only tech and AI related sectors with strong gains, other industries in the red. Interest rates with an increase.
My View: News-driven markets, often triggering strong reactions - a trend likely to become more common. The topic of tariffs has a significant short-term impact on the markets, leaving investors on edge. So far, the actual numbers have been somewhat modest. However, during his campaign, Trump had threatened to impose global tariffs of 10%-20% and an extraordinary 60% tariff on China.
Today’s rally is not broad based as most US sectors, except tech, are trading in the red. I avoid chasing such market fluctuations driven by speculative investors. This rally could be short-lived. Instead, I maintain a steady approach, focusing on capitalizing on opportunities as they arise, e.g. volatility and semiconductors, long respectively short (ETF).
21.01.25 - Trump 2.0 - no euphoria 2.0
A very busy Donald Trump on his first day of being president, signing a high number of executive actions in different subjects.
Markets: China’s stock market up last night as tariffs not (yet) on agenda. Cryptos down as no acts on this topic (yet). Interest rates down as tariffs seem delayed and maybe less high as feared. US dollar with some reversal today after the strong drop yesterday.
My View: Markets showed a big wave of euphoria after Donald Trump was elected as the 47th president of the United States of America back in November. A lot of optimism got priced in. Today, there seems so far no second wave of euphoria to establish after the inauguration of Donald Trump.
A high level of uncertainty keeps investors on a cautious wait-and-see approach before making the next bets. As I already mentioned several times before, from now on, there can be any day during the coming 1’460 days ahead, when financial markets suddenly see a big reaction on news coming from the White House. This potential of rollercoaster has to be kept in mind as short-term market fluctuations driven by political news can be dramatic. However, it is important to keep the focus on long-term fundamentals, such as corporate earnings, economic growth, and industry trends as sharp market moves driven by political developments are often only temporary. Strong (over-)reactions always bear chances to benefit.
20.01.25 - Inauguration Day
Donald Trump returns to the White House today, promising the high number of 200 executive orders right after his inauguration. Already a lot of speculation came up during weekend and the last hours on potential topics in his wave of first-day orders, ranging from TikTok, crypto regulation, and expanded oil drilling initiatives etc.
Markets: Asset classes reacting on the speculative news, like cryptos saw a jump, now giving back some of the gains. The US dollar shows weakness as tariffs should not be on the agenda on the first day.
US markets see scheduled closure for Martin Luther King Jr. Day.
My View: A lot of speculation dominates the news flow about the first steps Donald Trump will take after his inauguration.
All eyes are now on the first papers. This could lead to a rise in volatility. A situation which could appear any day from now on going forward.
I do not add new bets till a clear picture about Donald Trump’s first steps arises.
17.01.25 - China’s economy - strong finish in 2024
China reported important economic data this morning. China’s economy achieved a 5% growth rate in 2024, marking a slowdown versus previous year’s 5.2% growth rate. This was inline with the official target set.In the fourth quarter, gross domestic product expanded 5.4%, higher than the estimated 5.0% by analysts. This growth was primarily driven by a 6.2% increase in manufacturing output (estimated 5.4%) while retail sales rose 3.7%, higher than the forecasted 3.5%.
Markets: Chinese stock markets showed only modest reaction. The Shanghai Composite Index experience slight gains while the Hang Seng Index rose 0.31%.
My View: The data set looks strong on first sight. The growth was bolstered by strong manufacturing and export activities. Government stimulus efforts kicked in. Economic data came in above estimates.
However, the question is, how investors look at the China, seeing the glass half empty or full.
Concerns persist regarding weak consumer sentiment, deflationary risks, and skepticism about the reliability of official data. Additionally, potential US tariff increases under US president Donald Trump could pose some more uncertainties for China's economic outlook.
I am in minority with my view, seeing the glass half full, sharing an optimistic perspective. China’s stock markets have the potential to rise and the downside is rather limited. With retail sales picking up, there is a potential for the consumer and internet stocks which show attractive valuations compared to global and US peers. I expect more stimulus to come, latest presented at the 14th National People's Congress (NPC) in beginning of March.
Bear in mind, the stock indices might show higher volatility during the coming weeks with all the politics. Any dip can be seen as an attractive entry point for a long-term allocation.
Become a member to access more valuable market updates like this.
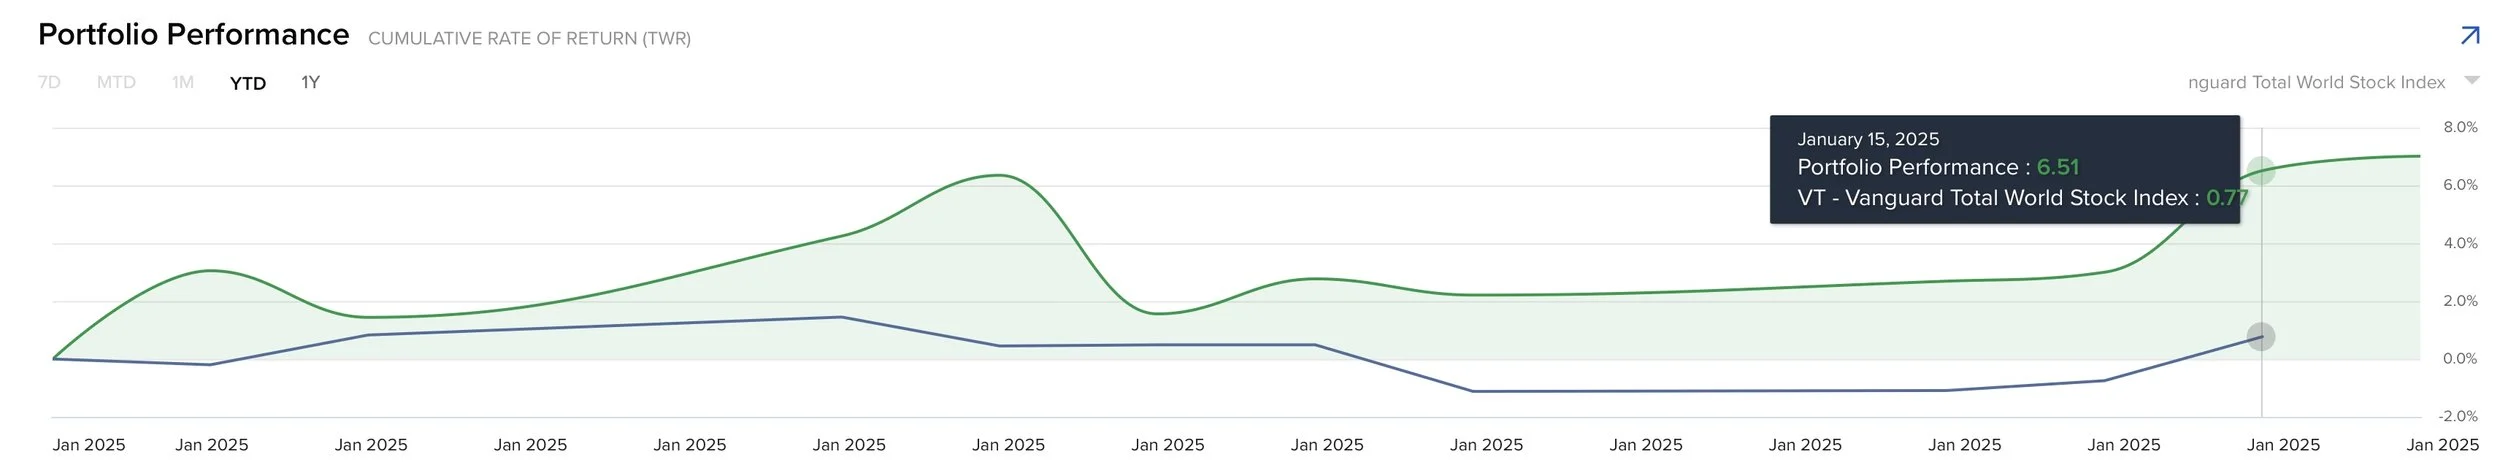
16.01.25 - Performance ETFMandate Portfolio
Successful start 2025 despite market turmoil thanks to tactical adjustments short-term!
Portfolio Performance YTD: +6.51%
Market Performance: ACWI* +0.92%
DAX +3.34%
Nasdaq +1.05%
My View: I had anticipated potential market turbulence during the second half of December (see Market Insights) and proactively hedged the portfolio and equity positions by taking short positions and going long on volatility.
*MSCI all Countries World Index
15.01.25 - Action-packed day - inflation concerns fade
Wednesday, a day packed with crucial economic data and the kickoff of earnings season.
UK: inflation lower than expected. Inflation rate 2.5% YoY vs. 2.6% consensus estimate.
Germany: economy continues to shrink, as expected, for second year in a row. German GDP -0.2% YoY (2024) vs. -0.3% YoY (2023).
US: inflation data inline: CPI 0.4% MoM and 2.9% YoY, both as expected.
Corporate earnings: reporting season started with US banks. JPMorgan, Goldman Sachs, BlackRock, WellsFargo, Citigroup, all banks reported sales and earnings above estimates.
Markets: Inflation prints are taken positive for risk assets.
UK: interest rates decline based on latest inflation figures, pound rises following recent slump through market turmoil.
Germany/Europe: Stock indices rise with some regained confidence.
US: Stock Futures jump after inflation report and strong bank earnings, US yields and US dollar decline.
Sentiment: No sharp reaction, only little move from “extreme fear” to fear level.
My View: As I mentioned few days ago, I did not share the common view that inflation would skyrocket. Therefore, today’s release is not much of a surprise to me.
I am happy with the latest tactical calls mirroring this view: buying US longterm Treasuries (leveraged ETF, 07.01.25), longterm UK Gilts (leveraged ETF, 14.01.25), hedging the US dollar (14.01.25), buying some pounds (14.01.25), adding long volatility (leveraged ETF, 16.12.24) and shorten the semiconductor sector (leveraged ETF, 07.01.25).
I continue to believe that interest rates will stabilize and show a tendency to decline, returning to levels observed a few weeks and months ago.
It is fair to say that increasing equity exposure as a tactical move could also be considered an investment opportunity. However, given my current equity allocation and significant volatility currently affecting equities, I opted not to add more risk to this asset class. Additionally, I am not yet convinced that today’s equity rally will prove to be sustainable.
Become a member to access more valuable market updates like this.
14.01.25 - Attempt to rebound after inflation reading
The producer price index (PPI) rose 0.2% in December, less than the 0.4% increase in November and below the consensus estimate for 0.3%. Producer prices are a leading indicator of consumer prices. The release is the first of two key inflation readings published this week.
Markets: Markets and risk assets seem to stabilize since the latter part of yesterday’s trading session. Asian indices showed a strong rebound, European and US markets try to follow however rather shy. Interest rates are moving sideways.
My View: Markets are attempting to stabilize, but in my view, the rebound appears too modest following the recent drop in stock prices. Before increasing my equity exposure - whether by closing my short positions or buying additional stocks - I want to see a more decisive upward movement and a clearer indication of investor confidence.
As investors seem to overreact on the inflation topic, I expect interest rates to normalize and return to lower levels on some point. At the same time, the US dollar could lose some ground following its recent rally. I have started hedging a portion of my USD exposure against the Swiss franc at the price of 0.91702.
As the same story is cooked in the UK, I decided to gain some exposure to longterm UK Gilts (UK government bonds) to my portfolio today, implementing this strategy through an ETF.
Become a member to access more valuable market updates like this.
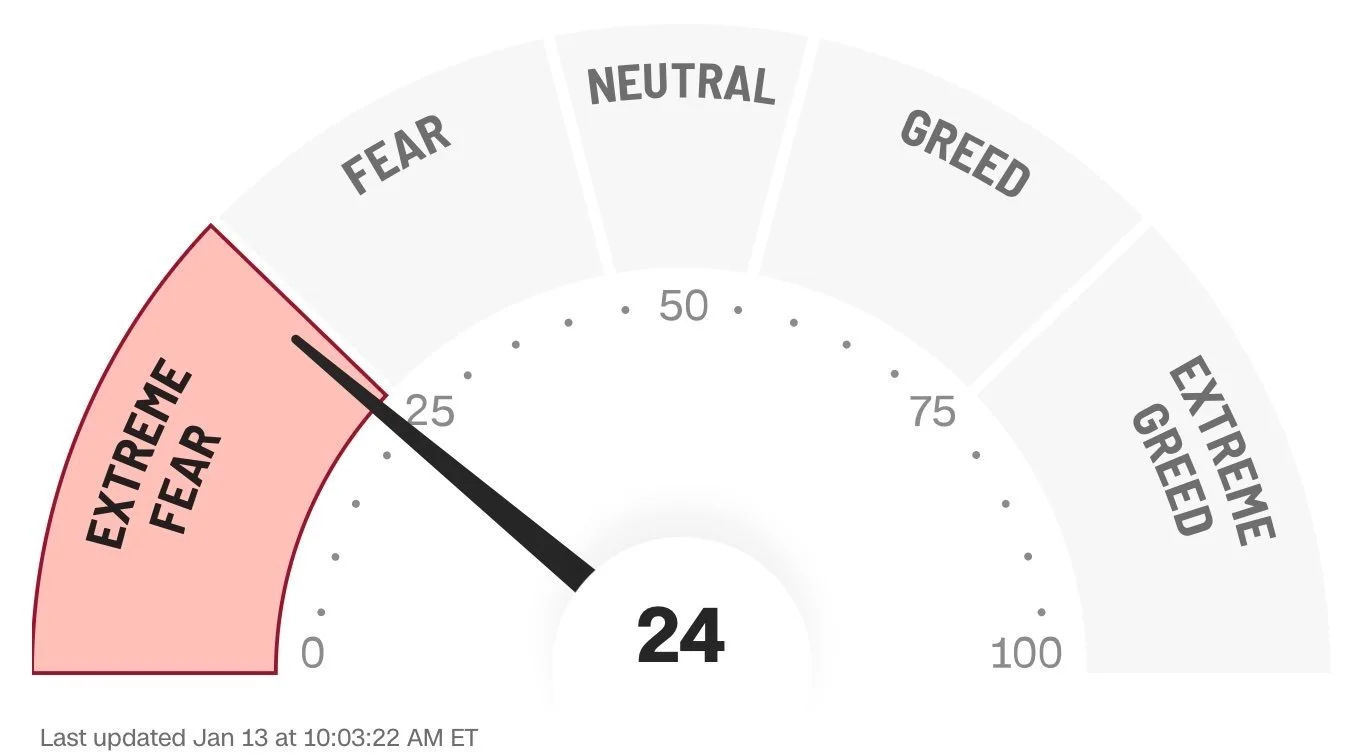
13.01.25 - Extreme fear hits markets
The CNN Fear & Greed Index hits the “Extreme Fear” level, indicating the risk aversion among investors. The index is a measure of market sentiment, based on factors such as volatility, stock price momentum, market breadth, and demand for safe assets like bonds.
Markets: Market sell-off continues on a broad base as interest rates and volatility rise.
My View: Cross-asset correlation starts to increase indicating a heightened market uncertainty and the broader market correction. Investors got caught on the wrong foot starting the investment year 2025 with pure optimism around. In December, the cash levels hit the lowest level. All-in stance without any hedging as the put/call ratio is still on low levels.
The Fear & Greed Index is a contrarian indicator. A “extreme fear” level normally indicates a buying opportunity. However, as the momentum of increasing interest rates might continue, further downward pressure on equities cannot be ruled out in the short-term. Markets seem to be close to some support levels. Before I go back to increase my risk exposure, I would like to see these technical support levels to be successfully tested.
Based on the latest market patterns, the pendulum could easily hit the downside as an overreaction could be seen for once also on the negative side. A negative momentum is just about to start and the speculative traders did not yet leave the market.
Become a member to access more valuable market updates like this.
13.01.25 - China surprises
China’s exports surged in December by 10.7% from a year earlier, higher than the expected 7.3%, while imports were up 1% (expected -1.5%). Ahead of Donald Trump’s return to the White House, China’s trade surplus hits a record high.
Markets: Chinese indices managed to recover some of the losses after the release, but ended the session in the red. Downward pressure in equity markets across the globe amid rising U.S. interest rates and risk aversion.
My View: somehow the upbeat in exports does only surprise on first sight. It seems companies rushed to deliver goods out of the country before Donald Trump returns to the White House. More evidence about China’s economy with data on GDP growth, retail sales, or industrial production will follow on coming Friday. This has room to sway market sentiment. I remain optimistic that Chinese stocks have an upside potential, favoring the internet sector, implemented via an ETF.
Become a member to access more valuable market updates like this.
12.01.25 - Key week ahead
During the coming week, an important set of economic data will be released, alongside the kickoff of earnings season. Wednesday could become a hot day. The big banks like JPMorgan, Citigroup, BlackRock, Goldman Sachs and Wells Fargo are set to report their fourth quarter results. On the same day, new inflation data will be released.
Already on Monday morning, investors will closely watching economic data out of China, including the latest import/export figures followed by a substantial data release on Friday, featuring GDP growth and other critical indicators.
Markets: - (only cryptos are trading over the weekend, sideways in a wide range)
My View: a crucial week for financial markets could be ahead of us. After the hot job report on Friday, the fear of inflation is definitely back and could shake up markets further in the short-term, in case higher inflation should be confirmed and interest rates continue to rise.
Regarding China, the next data set could also give the market a new direction. Chinese stock markets have been underperforming global indices for several years, especially since pandemics. In my view, today, the glass is half full, while investors have rather a pessimistic stance, also with the threat of potential tariffs, several time announced by Trump. A lot of this is already priced in. Therefore, any positive surprise could lift stock prices in that region. At latest during the National People’s Congress in beginning of March, the government will come up with more stimulus package to support the Chinese economy.
Become a member to access more valuable market updates like this.
10.01.25 - Hot job report
As revealed by this afternoon's data, job growth in the US during December was significantly stronger than anticipated. Non-farm payrolls surged by 256’000 for the month, up from 212’000 in November and way above of the 155’000 forecasted. As a consequence, the unemployment rate came down to 4.1% (4.2% expected). The latest US job data released this afternoon came much better . The 10-year Treasury yield spiked to highest level since late 2023.
Markets: as a first reaction, interest rates and US dollar up. Stocks, cryptos, gold all down with tech and small & mid cap stocks suffering the most while energy and material sectors outperform with rising commodity prices.
My View: The year begins on a tense note, mirroring the last days on financial markets in 2024. As a consequence of rising uncertainties, investors eye on any hint by any economic release. Elevated volatility is likely to persist in the near term, keeping markets on a knife's edge until a clearer trend emerges and the pendulum begins to calm.
I continue to wait on the side-line adding more risks to my portfolio. However, I am ready for buying opportunities which could be around the corner. Better job data should actually be taken as good news regarding the overall US economy. However, investors ‘fear’ less rate cuts by the Fed than anticipated before.
Become a member to access more valuable market updates like this.
08.01.25 - All eyes on interest rates
Rumors about milder tariffs followed by Donald Trumps dementi pushed the interest rates and the inflation topic back in focus. The anticipated rate cuts by Wall Street wane. As a result, interest rates across major economies are going up, with a tilt to the longer side.
Tonight the Fed will release the minutes from its latest FOMC meeting back in December with its latest rate cut. The detailed records could provide valuable insights regarding the anticipated interest rate path in the US.
Markets: The US 10-year Treasury yield surpassed the 4.7%. With higher interest rates, more capital intense small & mid cap stocks suffer.
My View: Seems like the market wants to test the highs from October 2023 hitting the 5%.
I did not align with the prevailing consensus favoring significant rate cuts, nor do I now share investors’ heightened concerns about potential inflation. As a result, I expect interest rates to stabilize with some potential to decline. However, there is room for rates temporarily overshoot on the upside, as markets have shown a tendency to overreact recently.
It could be, that I was a slightly early adding exposure to the long-term Treasuries.
Should investors’ nervousness persist for several more days the overall sentiment could turn negative. Flight to quality kicks in. The hunt for safety and therefore US Treasuries will put yields lower again.
The last days could give a feeling what to expect during coming weeks and months. Any statement of president Trump and Elon Musk can move markets heavily in either direction as seen the last few days. An overall higher volatility level could be a reasonable consequence. Therefore the long volatility position implemented via ETF remains in my portfolio.
Become a member to access more valuable market updates like this.
07.01.25 - Fading momentum in (over)crowded trades
A notable shift in direction today in some of the most crowded trades like Palantir, Tesla, AppLovin, Nvidia etc. These stocks have been key drivers of Nasdaq’s recent rally. Today, after Nvidia set a new all-time high right after the opening bell, the positive momentum faded away and a wave of profit-taking set in as investors moved to lock in some gains.
Markets: Nasdaq Index with another significant move, dropping more than 1%. Cryptos heavily down. Interest rates are rising, faster on the longer end with the US 10-year yield close to 4.7%. European stock indices for once in the green. Gold and the US dollar gain ground with increasing uncertainties.
My View: The washout of crowded trades can be seen as both healthy and necessary, providing a reset for stocks that have experienced significant momentum. While a pause is a natural market response, the duration and severity of this pullback remain uncertain.
I took the opportunity to increase my exposure to US long-term Treasuries through an ETF, viewing it as a tactical investment move. Additionally, I took a short position on semiconductors today via an ETF, targeting a short-term investment opportunity.
I am also maintaining my short positions but have adjusted the stop limits lower to account for a potential rebound.
Become a member to access more valuable market updates like this.
06.01.25 - Hydrogen sector - strong gains
The US Department of the Treasury released today final rules for clean hydrogen production tax credit, established by the inflation reduction act. The final rules should move projects forward and help grow the industry. Companies such as Plug Power, among others, stand to benefit.
Markets: Based on the news, the hydrogen sector is among today’s top-performing industries. The sector ETF has surged almost 6%, marking a notable recovery from recent lows.
My View: Since the hype in 2021 and 2022, the sector related stocks did rather poor. Companies suffered from rising interest rates and growth fell rather short of expectations. While the sector has benefited from support under Biden’s administration, the outlook with Trump as the new president could be rather weak. However, this is already priced in since the Election Day back in November.
If the sector regains attention and builds on some positive momentum, even modest inflows could help lift these stocks from their current lows. However, volatility is likely to remain elevated, along with associated risks. I remain invested, as I believe hydrogen technology holds significant long-term potential.
Become a member to access more valuable market updates like this.
06.01.25 - Chip sector lifts market despite higher inflation data
German inflation data released today shows an uptick, back to the 3% mark. In the US, the chip market is the top gaining sector today, the day when Donald Trump is going to be confirmed by the Congress as the 47th US president.
Markets: US tech index Nasdaq again with a change above the 1% mark, this time on the upside. Chip sector in the lead, could also lift European stocks. Interest rates on the rise while cryptos show big plus.
My View: Market volume is back to be more normal as traders are back from the holiday seasons. Therefore swings could turn back to be more normal.
With the nomination of the new US president, a next wave of Trump euphoria could start as mainly risk assets are the top gainers, lead by the chip sector.
The latest inflation data in Europe highlights the already mentioned dilemma of the ECB, rising inflation with sluggish growth. Not a bullish case for European stocks.
Become a member to access more valuable market updates like this.